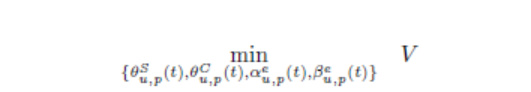
V is the linear objective of these four variables, and all of the variables are 3x100x100 matrix.
It is hard to directly solve with the CVX solver.
Does anyone have better solutions?

V is the linear objective of these four variables, and all of the variables are 3x100x100 matrix.
It is hard to directly solve with the CVX solver.
Does anyone have better solutions?
Are you saying that there are 1.2e5 variables? That doesn’t sound very big for an LP. But you haven’t shown us the objective function or constraints (wouldn’t be a very interesting LP without some constraints). We don’t even know it’s really an LP. Is it actually a MILP? (can be big difference in terms of solution difficulty)
Also note that CVX is a modeling front end, not a solver. The choice of solver can greatly affect solution speed and robustness (the commercial solvers available under CVX are generally faster and more robust than the free solvers).
Honestly, i’ m a beginner of optimization area. The constraints are as followings:
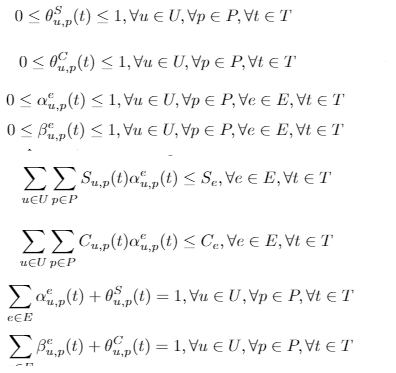
The S_{u,p}(t), S_{e} are both the given parameters. There are 24 time slots. And Some specific details can be ignored here. I think it should be a LP problem and i tried to solve it with CVX gurobi. It will cost about 50 mins for a optimization in per time slot, only with the 3e4 variables. And memory error for 1.2e5 variables. (16G, i7 cpu).
Many thanks for your help!