
How to minimize my log_det function in convex programming
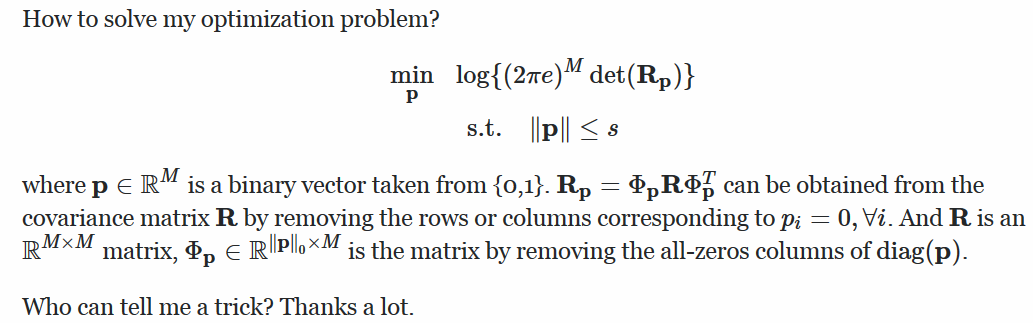
I think, we can neglect the L0 norm constraint, because it can be relaxed by L1 norm. The difficulty to me is how to formulate R_p matrix as a linear function of p vector, then it maybe accepted by CVX.
Yes, I agree. So how to formulate R_p matrix as a linear function of p vector, such that it maybe accepted by CVX?
If M is small enough, you could you use brute force evaluation of the objective function for all possible values of p.
Otherwise, perhaps use a general purpose mixed integer nonlinear solver and recognize/accept that you might not get the global optimum, or try posting at https://www.or-exchange.org/ or http://scicomp.stackexchange.com/ .